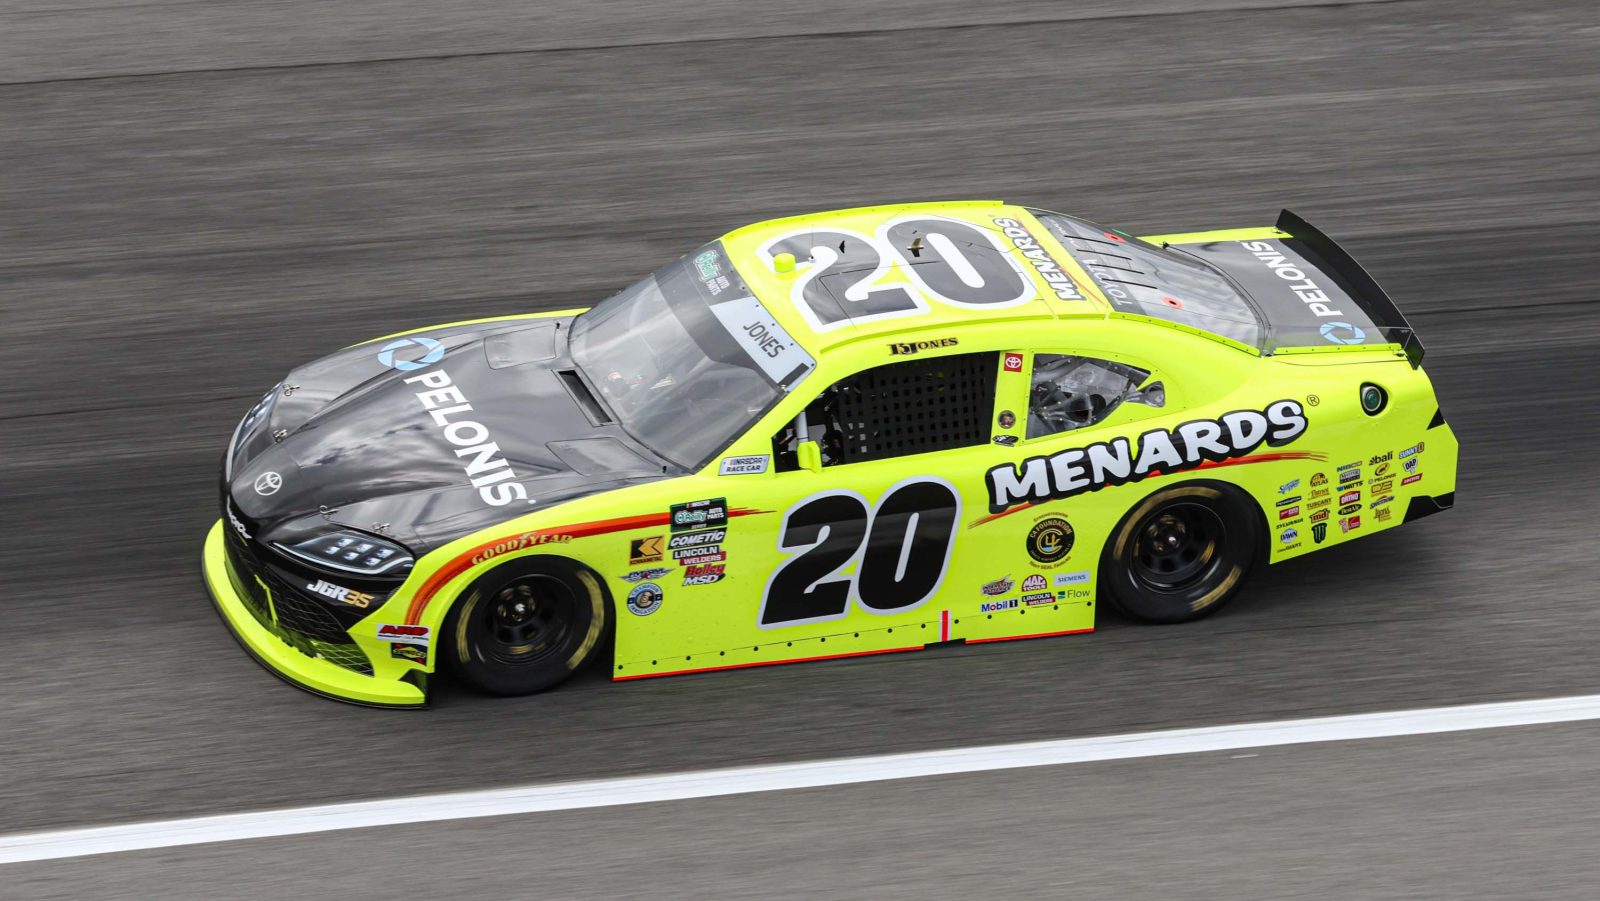
Joe Jones and Maryanne Pace-Jones, the parents of NASCAR O’Reilly Auto Parts Series driver Brandon Jones, have filed a petition in U.S. Tax Court, after the IRS imposed a total of $749,431.20 in Income Tax Deficiencies and Proposed Penalties for the couple in 2023 and 2024 – after determining that the management of his son’s career was not a legitimate business enterprise.
The petition, filed on November 6, challenges the findings of the IRS, while also requesting that the Tax Court determine that Form 1040 from 2023 and 2024 are accurate, that Brandon Jones Racing LLC was an activity engaged for profit, that there are no deficiencies, addition to tax, penalties, or other amounts due for those years, and that the Respondent has burden of proof in the matter.
In the filing, the couple, which owns and operates Brandon Jones Racing LLC, outlined the ways in which Joe Jones’ worked on behalf of his son, Brandon, throughout his entire racing career, and how it was a profit-seeking venture.
Over the last 15 years, the couple has operated Brandon Jones Racing LLC, with the main purpose of setting up professional racecar driver Brandon Jones with rides in all levels of NASCAR’s National and Regional Series, and has done so since 2013, working with Turner Motorsports, Richard Childress Racing, Joe Gibbs Racing, JR Motorsports, and others.
Of note, Joe Jones is the Executive Chairman of Rheem, a global manufacturer of heating, ventilation, air-conditioning, water-heating, and related products and systems, a company he’s held office with since 2007, and holds investments with multiple top-tier financial institutions. It’s that business and investment expertise that Jones believes has aided his venture to manage and operate Brandon Jones Racing LLC.
The filing states that Brandon Jones Racing LLC’s business “is to promote and develop a professional race car driver, contract with established NASCAR racing teams for driving services and racing opportunities, obtain, administer, and service sponsorships, and generate income from racing winnings, sponsor fees, royalties, licensing, and merchandising.”
In an attempt to convey “businesslike manner and profit motive”, the petitioner says the company maintained and used a business checking account, maintained adequate books and records regarding income and expenses, engaged with an Account Firm (James & Company, Certified Public Accountants) to file its tax forms, and even issued 1099 Forms to a number of organizations over the two-year period.
The filing also mentions that Brandon Jones Racing LLC elected to sign a new agreement with Joe Gibbs Racing, starting in 2025, after its two-year stint with JR Motorsports generated “the lowest earnings for [the company] since 2015”. This new deal with JGR was designed to “improve competitive opportunities, sponsorship prospects, and overall profitability” while also working towards advancing Jones to the NASCAR Cup Series.
Joe Jones has “managed and operated [Brandon Jones Racing LLC]’s business, including, but not limited to, overseeing racing operations, sponsorship activities, contractual relationships, financial matters, and other business matters” since 2012, and maintains that there was a significant amount of time output for him to occupy this role.
Jones maintains that he spent about 20 hours a week working for the company, while also traveling to numerous racetracks across the United States with driver Brandon Jones, who competed full-time in the NASCAR O’Reilly Auto Parts Series for JR Motorsports. That doesn’t include the intense commitment from his son – including 33 at-track meet-and-greets, 30 personal-appearance engagements, six four-hour content-production sessions, and eight two-hour content-productions sessions, plus ongoing social-media initiates across Facebook, Instagram, Twitter, and Fan Club.
The petitioner states that the revenue taken in by Brandon Jones Racing LLC has grown substantially, growing from $18,920 in 2012 to as high as $1,173,398 in 2019. In 2024, the company’s gross revenue was $514,688. However, during 2023 and 2024, Brandon Jones Racing LLC incurred expenses of more than half a million dollars in contract labor, as well as $250,000, which the company had to contribute towards the cost of racing the JR Motorsports entry. Jones claims had it not been for amortization deductions and contributions towards the Racing Fees, the company would have reported a net income under $100,000 in both years.
In choosing to file this petition, the couple believes that the IRS has made several errors in evaluating their submitted tax forms, including the disallowing of millions of dollars of incurred expenses ($1,687,908). as well as classifying the income earned from Brandon Jones Racing LLC ($944,067) as ‘Other Income’.
An initial notice from the IRS disallows income of $944,067 and reclassifies it as “Other Income” on the basis that the company’s activity doesn’t meet the guidelines of carrying on a trade or a business, while also disallowing expenses of $1,687,908, labor expenses of $1,356,381, and “substantially all expenses incurred by [Brandon Jones Racing LLC].
The petitioners say that an Accounting Firm was hired in order to prepare the 2023 Form 1040 and 2024 Form 1040, including Schedules C for Brandon Jones Racing LLC, which is the main issue at hand with this objection by the IRS, and that with more than 25 years of experience in their fields, that their outputs were trustworthy and in good faith.
“The contents of the Notice are erroneous, unfair, unreasonable, arbitrary, and capricious.